• Pay Online
  • 9info@ivy-cpa.com
  • !(786) 227-6928
  • A ? R G ; B =
  • }Appointments
  • lMap
Close
Website Privacy Policy

Effective: February 7, 2022

Thanks for visiting our website. Our mission is to create a web based experience that makes it easier for us to work together. Here we describe how we collect, use, and handle your personal information when you use our websites, software, and services (“Services”).

What & Why

We collect and use the following information to provide, improve, and protect our Services:

Account information. We collect, and associate with your account, the information you provide to us when you do things such as sign up for your account, opt-in to our client newsletter or request an appointment (like your name, email address, phone number, and physical address). Some of our Services let you access your accounts and your information via other service providers.

Your Stuff. Our Services are designed to make it simple for you to store your files, documents, comments, messages, and so on (“Your Stuff”), collaborate with others, and work across multiple devices. To make that possible, we store, process, and transmit Your Stuff as well as information related to it. This related information includes your profile information that makes it easier to collaborate and share Your Stuff with others, as well as things like the size of the file, the time it was uploaded, collaborators, and usage activity. Our Services provide you with different options for sharing Your Stuff.

Contacts. You may choose to give us access to your contacts (spouse or other company staff) to make it easy for you to do things like share and collaborate on Your Stuff, send messages, and invite others to use the Services. If you do, we’ll store those contacts on our servers for you to use.

Usage information. We collect information related to how you use the Services, including actions you take in your account (like sharing, viewing, and moving files or folders). We use this information to improve our Services, develop new services and features, and protect our users.

Device information. We also collect information from and about the devices you use to access the Services. This includes things like IP addresses, the type of browser and device you use, the web page you visited before coming to our sites, and identifiers associated with your devices. Your devices (depending on their settings) may also transmit location information to the Services.

Cookies and other technologies. We use technologies like cookies to provide, improve, protect, and promote our Services. For example, cookies help us with things like remembering your username for your next visit, understanding how you are interacting with our Services, and improving them based on that information. You can set your browser to not accept cookies, but this may limit your ability to use the Services.

Marketing. We give users the option to use some of our Services free of charge. These free Services are made possible by the fact that some users upgrade to one of our paid Services. If you register for our free Services, we will, from time to time, send you information about the firm or tax and accounting tips when permissible. Users who receive these marketing materials can opt out at any time. If you do not want to receive marketing materials from us, simply click the ‘unsubscribe’ link in any email.

We sometimes contact people who do not have an account. For recipients in the EU, we or a third party will obtain consent before contacting you. If you receive an email and no longer wish to be contacted by us, you can unsubscribe and remove yourself from our contact list via the message itself.

Bases for processing your data. We collect and use the personal data described above in order to provide you with the Services in a reliable and secure manner. We also collect and use personal data for our legitimate business needs. To the extent we process your personal data for other purposes, we ask for your consent in advance or require that our partners obtain such consent.

With Whom

We may share information as discussed below, but we won’t sell it to advertisers or other third parties.

Others working for and with Us. We use certain trusted third parties (for example, providers of customer support, eSign and IT services) to help us provide, improve, protect, and promote our Services. These third parties will access your information only to perform tasks on our behalf in compliance with this Privacy Policy, and we’ll remain responsible for their handling of your information per our instructions. For a list of trusted third parties that we use to process your personal information, please see our third party vendors below.

Other users. Our Services display information like your name, profile picture, device, and email address to other users in places like your user profile and sharing notifications. You can also share Your Stuff with other users if you choose. When you register your account with an email address on a domain owned by your employer or organization, we may help collaborators and administrators find you and your team by making some of your basic information—like your name, team name, profile picture, and email address—visible to other users on the same domain. This helps you sync up with teams you can join and helps other users share files and folders with you. Certain features let you make additional information available to others.

Team Admins. If you are a user of a team, your administrator may have the ability to access and control your team account. Please refer to your organization’s internal policies if you have questions about this. If you are not a team user but interact with a team user (by, for example, joining a shared folder or accessing stuff shared by that user), members of that organization may be able to view the name, email address, profile picture, and IP address that was associated with your account at the time of that interaction.

Law & Order and the Public Interest. We may disclose your information to third parties if we determine that such disclosure is reasonably necessary to: (a) comply with any applicable law, regulation, legal process, or appropriate government request; (b) protect any person from death or serious bodily injury; (c) prevent fraud or abuse of our platform or our users; (d) protect our rights, property, safety, or interest; or (e) perform a task carried out in the public interest.

Stewardship of your data is critical to us and a responsibility that we embrace. We believe that your data should receive the same legal protections regardless of whether it’s stored on our Services or on your home computer’s hard drive. We’ll abide by Government Request Policies when receiving, scrutinizing, and responding to government requests (including national security requests) for your data:

• Be transparent,
• Fight blanket requests,
• Protect all users, and
• Provide trusted services.

How

Security. We have a team dedicated to keeping your information secure and testing for vulnerabilities. We also continue to work on features to keep your information safe in addition to things like blocking repeated login attempts, encryption of files at rest, and alerts when new devices and apps are linked to your account. We deploy automated technologies to detect abusive behavior and content that may harm our Services, you, or other users.

User Controls. You can access, amend, download, and delete your personal information by logging into your account.

Retention. When you sign up for an account with us, we’ll retain information you store on our Services for as long as your account is in existence or as long as we need it to provide you the Services. If you delete your account, we will initiate deletion of this information after 30 days. But please note: (1) there might be some latency in deleting this information from our servers and back-up storage; and (2) we may retain this information if necessary to comply with our legal obligations, resolve disputes, or enforce our agreements.

Where

Around the world. To provide you with the Services, we may store, process, and transmit information in the United States and locations around the world—including those outside your country. Information may also be stored locally on the devices you use to access the Services.

EU-U.S. Privacy Shield and Swiss-U.S. Privacy Shield. When transferring data from the European Union, the European Economic Area, and Switzerland, We rely upon a variety of legal mechanisms, including contracts with our customers and affiliates. We comply with the EU-U.S. and Swiss–U.S. Privacy Shield Frameworks as set forth by the U.S. Department of Commerce regarding the collection, use, and retention of personal information transferred from the European Union, the European Economic Area, and Switzerland to the United States.

We are subject to oversight by the U.S. Federal Trade Commission. JAMS is the US-based independent organization responsible for reviewing and resolving complaints about our Privacy Shield compliance—free of charge to you. We ask that you first submit any such complaints directly to us via privacy@CountingWorks.com. If you aren’t satisfied with our response, please contact JAMS at https://www.jamsadr.com/eu-us-privacy-shield. In the event your concern still isn’t addressed by JAMS, you may be entitled to a binding arbitration under Privacy Shield and its principles.

Changes

If we are involved in a reorganization, merger, acquisition, or sale of our assets, your information may be transferred as part of that deal.

We may revise this Privacy Policy from time to time, and will post the most current version on our website. If a revision meaningfully reduces your rights, we will notify you.

Your Right to Control and Access Your Information

You have control over your personal information and how it is collected, used, and shared. For example, you have a right to:

• Erase or delete all or some of Your Stuff in your portal account.
• Change or correct personal data. You can manage your account and the content contained in it, as well as edit some of your personal data, through your portal account setting.
• Access and take your data. You can download a copy of Your Stuff in a machine readable format by visiting the portal.

Contact

Your personal information is controlled by CountingWorks, Inc. Have questions or concerns about CountingWorks, our Services, and privacy? Contact our Data Protection Officer at privacy@CountingWorks.com. If they can’t answer your question, you have the right to contact your local data protection supervisory authority.

Third Party Vendors

Box.com
HelloSign
Google
Rackspace
DialogTech
Wufoo.com
Sendgrid
Twilio
Plausible
Amazon Web Services
Yext
MailGun
Bright Local
TransUnion
Terms of Service
Effective: February 7, 2022

Thanks for using our services! These terms of service (“Terms”) cover your use and access to our services, client software and websites ("Services"). We use CountingWorks, Inc. as our technology platform to enable us to provide our services in a secure environment. By using our Services, you’re agreeing to be bound by these Terms, and our Privacy Policy. If you’re using our Services for an organization, you’re agreeing to these Terms on behalf of that organization.

Your Stuff & Your Permissions

When you use our Services, you provide us with things like your files, content, messages, contacts, and so on (“Your Stuff”). Your Stuff is yours. These Terms don’t give us any rights to Your Stuff except for the limited rights that enable us to offer the Services.

We need your permission to do things like hosting Your Stuff, backing it up, and sharing it when you ask us to. Our Services also provide you with features like eSign, file sharing, email newsletters, appointment setting and more. These and other features may require our systems to access, store, and scan Your Stuff. You give us permission to do those things, and this permission extends to our affiliates and trusted third parties we work with.

Sharing Your Stuff

Our Services let you share Your Stuff with others, so please think carefully about what you share.

Your Responsibilities

You’re responsible for your conduct. Your Stuff and you must comply with applicable laws. Content in the Services may be protected by others’ intellectual property rights. Please don’t copy, upload, download, or share content unless you have the right to do so. We may review your conduct and content for compliance with these Terms. With that said, we have no obligation to do so. We aren’t responsible for the content people post and share via the Services.

Help us keep you informed and Your Stuff protected. Safeguard your password to the Services, and keep your account information current. Don’t share your account credentials or give others access to your account.

You may use our Services only as permitted by applicable law, including export control laws and regulations. Finally, to use our Services, you must be at least 13, or in some cases, even older. If you live in France, Germany, or the Netherlands, you must be at least 16. Please check your local law for the age of digital consent. If you don’t meet these age requirements, you may not use the Services.

Software

Some of our Services allow you to download client software (“Software”) which may update automatically. So long as you comply with these Terms, we give you a limited, nonexclusive, nontransferable, revocable license to use the Software, solely to access the Services. To the extent any component of the Software may be offered under an open source license, we’ll make that license available to you and the provisions of that license may expressly override some of these Terms. Unless the following restrictions are prohibited by law, you agree not to reverse engineer or decompile the Services, attempt to do so, or assist anyone in doing so.

Beta Services

We sometimes release products and features that we are still testing and evaluating. Those Services have been marked beta, preview, early access, or evaluation (or with words or phrases with similar meanings) and may not be as reliable as other non-beta services, so please keep that in mind.

Our Stuff

The Services are protected by copyright, trademark, and other US and foreign laws. These Terms don’t grant you any right, title, or interest in the Services, others’ content in the Services, CountingWorks and our trademarks, logos and other brand features. We welcome feedback, but note that we may use comments or suggestions without any obligation to you.

Copyright

We respect the intellectual property of others and ask that you do too. We respond to notices of alleged copyright infringement if they comply with the law, and such notices should be reported to legal@CountingWorks.com. We reserve the right to delete or disable content alleged to be infringing and terminate accounts of repeat infringers. Our designated agent for notice of alleged copyright infringement on the Services is:

Copyright Agent
CountingWorks, Inc.
2549 Eastbluff Drive #448
Newport Beach, CA 92660
legal@CountingWorks.com

Termination

You’re free to stop using our Services at any time. We reserve the right to suspend or terminate your access to the Services with notice to you if:

(a) you’re in breach of these Terms,

(b) you’re using the Services in a manner that would cause a real risk of harm or loss to us or other users, or

We’ll provide you with reasonable advance notice via the email address associated with your account to remedy the activity that prompted us to contact you and give you the opportunity to export Your Stuff from our Services. If after such notice you fail to take the steps we ask of you, we’ll terminate or suspend your access to the Services.

We won’t provide notice before termination where:

(a) you’re in material breach of these Terms,

(b) doing so would cause us legal liability or compromise our ability to provide the Services to our other users, or

(c) we're prohibited from doing so by law.

Discontinuation of Services

We may decide to discontinue the Services in response to unforeseen circumstances beyond CountingWorks control or to comply with a legal requirement. If we do so, we’ll give you reasonable prior notice so that you can export Your Stuff from our systems.

Services “AS IS”

We strive to provide great Services, but there are certain things that we can't guarantee. TO THE FULLEST EXTENT PERMITTED BY LAW, CountingWorks AND ITS AFFILIATES, SUPPLIERS AND DISTRIBUTORS MAKE NO WARRANTIES, EITHER EXPRESS OR IMPLIED, ABOUT THE SERVICES. THE SERVICES ARE PROVIDED "AS IS." WE ALSO DISCLAIM ANY WARRANTIES OF MERCHANTABILITY, FITNESS FOR A PARTICULAR PURPOSE, AND NON-INFRINGEMENT. Some places don’t allow the disclaimers in this paragraph, so they may not apply to you.

Limitation of Liability

WE DON’T EXCLUDE OR LIMIT OUR LIABILITY TO YOU WHERE IT WOULD BE ILLEGAL TO DO SO—THIS INCLUDES ANY LIABILITY FOR CountingWorks OR ITS AFFILIATES’ FRAUD OR FRAUDULENT MISREPRESENTATION IN PROVIDING THE SERVICES. IN COUNTRIES WHERE THE FOLLOWING TYPES OF EXCLUSIONS AREN’T ALLOWED, WE'RE RESPONSIBLE TO YOU ONLY FOR LOSSES AND DAMAGES THAT ARE A REASONABLY FORESEEABLE RESULT OF OUR FAILURE TO USE REASONABLE CARE AND SKILL OR OUR BREACH OF OUR CONTRACT WITH YOU. THIS PARAGRAPH DOESN’T AFFECT CONSUMER RIGHTS THAT CAN'T BE WAIVED OR LIMITED BY ANY CONTRACT OR AGREEMENT.

IN COUNTRIES WHERE EXCLUSIONS OR LIMITATIONS OF LIABILITY ARE ALLOWED, CountingWorks, ITS AFFILIATES, SUPPLIERS OR DISTRIBUTORS WON’T BE LIABLE FOR:

i. ANY INDIRECT, SPECIAL, INCIDENTAL, PUNITIVE, EXEMPLARY, OR CONSEQUENTIAL DAMAGES, OR

ii. ANY LOSS OF USE, DATA, BUSINESS, OR PROFITS, REGARDLESS OF LEGAL THEORY.

THESE EXCLUSIONS OR LIMITATIONS WILL APPLY REGARDLESS OF WHETHER OR NOT CountingWorks OR ANY OF ITS AFFILIATES HAS BEEN WARNED OF THE POSSIBILITY OF SUCH DAMAGES.

IF YOU USE THE SERVICES FOR ANY COMMERCIAL, BUSINESS, OR RE-SALE PURPOSE, CountingWorks, ITS AFFILIATES, SUPPLIERS OR DISTRIBUTORS WILL HAVE NO LIABILITY TO YOU FOR ANY LOSS OF PROFIT, LOSS OF BUSINESS, BUSINESS INTERRUPTION, OR LOSS OF BUSINESS OPPORTUNITY. CountingWorks AND ITS AFFILIATES AREN’T RESPONSIBLE FOR THE CONDUCT, WHETHER ONLINE OR OFFLINE, OF ANY USER OF THE SERVICES.

Resolving Disputes

Let’s Try To Sort Things Out First. We want to address your concerns without needing a formal legal case. Before filing a claim against CountingWorks or our affiliates, you agree to try to resolve the dispute informally by contacting legal@CountingWorks.com. We’ll try to resolve the dispute informally by contacting you via email.

Judicial forum for disputes. You and CountingWorks agree that any judicial proceeding to resolve claims relating to these Terms or the Services will be brought in the federal or state courts of Orange County, California, subject to the mandatory arbitration provisions below. Both you and CountingWorks consent to venue and personal jurisdiction in such courts. If you reside in a country (for example, European Union member states) with laws that give consumers the right to bring disputes in their local courts, this paragraph doesn’t affect those requirements.

IF YOU’RE A U.S. RESIDENT, YOU ALSO AGREE TO THE FOLLOWING MANDATORY ARBITRATION PROVISIONS:

We Both Agree To Arbitrate. You and CountingWorks agree to resolve any claims relating to these Terms or the Services through final and binding arbitration by a single arbitrator. This includes disputes arising out of or relating to interpretation or application of this “Mandatory Arbitration Provisions” section, including its enforceability, revocability, or validity.

Arbitration Procedures. The American Arbitration Association (AAA) will administer the arbitration under its Commercial Arbitration Rules and the Supplementary Procedures for Consumer Related Disputes. The arbitration will be held in the United States county where you live or work, Orange County (CA), or any other location we agree to.

NO CLASS ACTIONS. You may only resolve disputes with us on an individual basis, and may not bring a claim as a plaintiff or a class member in a class, consolidated, or representative action. Class arbitrations, class actions, private attorney general actions, and consolidation with other arbitrations aren’t allowed. If this specific paragraph is held unenforceable, then the entirety of this “Mandatory Arbitration Provisions” section will be deemed void.

Controlling Law
These Terms will be governed by California law except for its conflicts of laws principles. However, some countries (including those in the European Union) have laws that require agreements to be governed by the local laws of the consumer's country. This paragraph doesn’t override those laws.

Entire Agreement

These Terms constitute the entire agreement between you and CountingWorks with respect to the subject matter of these Terms, and supersede and replace any other prior or contemporaneous agreements, or terms and conditions applicable to the subject matter of these Terms. These Terms create no third party beneficiary rights.

Waiver, Severability & Assignment

CountingWorks failure to enforce a provision is not a waiver of its right to do so later. If a provision is found unenforceable, the remaining provisions of the Terms will remain in full effect and an enforceable term will be substituted reflecting our intent as closely as possible. You may not assign any of your rights under these Terms, and any such attempt will be void. CountingWorks may assign its rights to any of its affiliates or subsidiaries, or to any successor in interest of any business associated with the Services.

Modifications

We may revise these Terms from time to time to better reflect:
(a) changes to the law,

(b) new regulatory requirements, or

(c) improvements or enhancements made to our Services.

If an update affects your use of the Services or your legal rights as a user of our Services, we’ll notify you prior to the update's effective date by sending an email to the email address associated with your account or via an in-product notification. These updated terms will be effective no less than 30 days from when we notify you.

If you don’t agree to the updates we make, please cancel your account before they become effective. By continuing to use or access the Services after the updates come into effect, you agree to be bound by the revised Terms.

Ivy Accounting , Tax & Advisors Accessibility Statement

Updated: June 2020.

General

Ivy Accounting , Tax & Advisors strives to ensure that its services are accessible to people with disabilities. Ivy Accounting , Tax & Advisors has invested a significant amount of resources to help ensure that its website is made easier to use and more accessible for people with disabilities, with the strong belief that every person has the right to live with dignity, equality, comfort and independence.

Accessibility on ivy-cpa.com

ivy-cpa.com makes available the UserWay Website Accessibility Widget that is powered by a dedicated accessibility server. The software allows ivy-cpa.com to improve its compliance with the Web Content Accessibility Guidelines (WCAG 2.1).

Enabling the Accessibility Menu

The ivy-cpa.com accessibility menu can be enabled either by hitting the tab key when the page first loads or by clicking the accessibility menu icon that appears on the corner of the page. After triggering the accessibility menu, please wait a moment for the accessibility menu to load in its entirety.

Disclaimer

Ivy Accounting , Tax & Advisors continues its efforts to constantly improve the accessibility of its site and services in the belief that it is our collective moral obligation to allow seamless, accessible and unhindered use also for those of us with disabilities.

In an ongoing effort to continually improve and remediate accessibility issues, we also regularly scan ivy-cpa.com with UserWay's Accessibility Scanner to identify and fix every possible accessibility barrier on our site. Despite our efforts to make all pages and content on ivy-cpa.com fully accessible, some content may not have yet been fully adapted to the strictest accessibility standards. This may be a result of not having found or identified the most appropriate technological solution.

Here For You

If you are experiencing difficulty with any content on ivy-cpa.com or require assistance with any part of our site, please contact us during normal business hours as detailed below and we will be happy to assist.

Contact Us

If you wish to report an accessibility issue, have any questions or need assistance, please contact Ivy Accounting , Tax & Advisors Customer Support as follows:

Email: info@ivy-cpa.com
Phone: (786) 227-6928

Ivy Accounting , Tax & Advisors
  • Home
  • About
    • About Us
    • Meet the Team
    • Referrals
    • Privacy Policy
    • Careers
    • FAQ
  • Services
    • Tax Preparation and Planning
    • Accounting & Bookkeeping
    • Business Consulting
    • Payroll
    • IRS Tax Problems
    • Audit, Review & Compilation
    • Quickbooks Services
    • Part Time CFO Services
    • Business Valuation
    • Cost Segregation
  • Learning Center
  • Community Involvement
    • Goldman Sachs Small Business 10,000
    • Client Appreciation 05/28/2015
    • Leadership Miami
  • Testimonials
  • 中文
    • 關於我們
    • 服務項目
    • 2018 年 新 税 法
  • Contact

Learning Center

Back to Article List

October 28, 2026

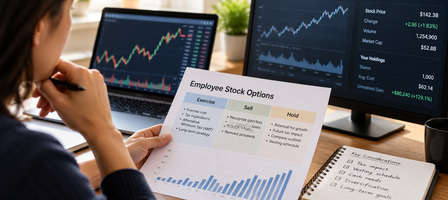
Employee Stock Options: When to Exercise, Sell, or Hold and Mitigate Taxes.

Share this article...
0 reviews
Rate this article
Employee Stock Options: When to Exercise, Sell, or Hold and Mitigate Taxes.

Employee stock options can be valuable, but they are not the same as ordinary wages, restricted stock, or an employer retirement plan. The tax result depends on the type of option, the exercise price, the stock’s fair market value, the date of exercise, and when the shares are sold.

The two major categories are:

  1. Nonqualified stock options, often called NSOs or NQSOs; and

  2. Incentive stock options, or ISOs, which are sometimes called qualified or statutory stock options.

The financial decision is usually more complicated than simply asking whether the stock price is rising. Exercising an option may require a large cash payment, trigger taxable income, increase concentration in one employer’s stock, and expose you to a decline in value before you sell.

This article explains the basic process and the principal tax and financial issues. Individual results can vary, especially when state taxes, alternative minimum tax, employment changes, large option grants, or private-company shares are involved.

PART ONE: NONQUALIFIED STOCK OPTIONS

What is a Nonqualified Stock Option? - A nonqualified stock option gives you the right to purchase company stock at a fixed price, called the exercise price, strike price, or grant price. The option normally has a vesting schedule (earning ownership over-time)and an expiration date.

For example, suppose you have the right to purchase 1,000 shares for $20 per share. If the stock is worth $50 per share, the option has a potential value of $30 per share, or $30,000 before taxes and transaction costs.

The difference between the stock’s fair market value and the exercise price is commonly called the spread or bargain element.

How exercising an NSO works - A typical exercise involves four basic steps:

  1. You notify the company or its stock-plan administrator that you want to exercise.

  2. You pay the exercise price.

  3. The company issues or transfers the shares to you.

  4. Taxes are withheld or collected on the taxable compensation created by the exercise.

The employer generally reports the spread from a nonqualified option exercise as compensation on Form W-2. The spread is ordinarily subject to federal income-tax withholding and employment taxes.

Assume the following:

  • 1,000 options.

  • Exercise price: $20 per share.

  • Fair market value at exercise: $50 per share.

  • Total exercise cost: $20,000.

  • Bargain element: $30,000.

The $30,000 spread is generally treated as wage income in the year of exercise. The employer may withhold taxes from cash compensation, require you to provide funds, or use a “sell-to-cover” arrangement in which some shares are sold to pay taxes.

The tax withholding may not equal your final tax liability. If the option exercise significantly increases your income, the amount withheld may be too low, particularly if the spread pushes you into a higher tax bracket or creates additional investment-income tax exposure.

Selling Immediately After Exercise - Many taxpayers exercise and sell the shares on the same day. This is sometimes called a same-day sale.

The principal advantage is that the stock price risk is limited. The compensation income is based on the spread at exercise, and selling immediately prevents a significant additional gain or loss from developing before the stock is sold.

Using the previous example:

  • Exercise price: $20,000.

  • Value of shares at exercise: $50,000.

  • Compensation income: $30,000.

  • Sale proceeds: approximately $50,000.

The $30,000 spread is included in wages. The stock’s tax basis is generally increased to reflect the amount already treated as compensation. If the shares are sold immediately for approximately $50,000, the subsequent capital gain or loss should generally be small, apart from commissions, market fluctuations, and other selling costs.

This strategy can be financially attractive when your objective is to receive the value of the option without continuing to own employer stock. It also avoids the risk that the stock will fall after exercise while you are still holding shares.

A same-day sale, however, eliminates the possibility of benefiting from future appreciation. It may also create a large current-year tax bill because the compensation income is recognized immediately.

Exercising and Holding the Shares - You may instead exercise the NSO and retain the shares. This creates a potential opportunity for future appreciation, but it also creates several risks.

First, you must pay the exercise price and the tax associated with the compensation income. In the example above, you may need to fund:

  • $20,000 to purchase the shares; and

  • Additional funds for taxes on the $30,000 compensation income.

Second, any future decline in the stock price could leave you with shares worth less than the amount you paid and the taxes you incurred.

Third, holding shares increases your financial dependence on your employer. Your wages, career prospects, and investment portfolio may all be tied to the same company. A stock price decline could occur at the same time that the company reduces compensation, lays off employees, or experiences financial problems.

The potential benefit is that appreciation after exercise generally qualifies for capital-gain treatment. Your holding period for the shares generally begins on the day after exercise. If you hold the shares for more than one year before selling, the post-exercise appreciation may qualify as long-term capital gain rather than short-term capital gain.

Financial Considerations Before Exercising - Before exercising and holding NSO shares, consider:

  • How much cash is required for the exercise?

  • How much tax will be due?

  • Is the stock publicly traded?

  • Are there trading restrictions or blackout periods?

  • Could the stock decline substantially?

  • How much of your net worth would be invested in employer stock?

  • What would happen if you left the company?

  • How long before the options expire?

  • Could the company be acquired or go public?

  • Are you relying on the shares to pay a near-term expense?

Publicly traded stock provides greater liquidity, but liquidity does not eliminate risk. A private-company option may be more difficult to value and sell. You may have to hold the shares for years without a market, and a future financing round or public offering may not occur.

Tax Strategies For NSOs

1. Exercise and sell immediately - A same-day sale can reduce market risk and prevent a large difference between the value used to calculate compensation income and the eventual sale proceeds.

This may be appropriate when your primary objective is diversification or obtaining cash rather than maintaining a long-term investment in the company.

2. Exercise in stages - Instead of exercising all options at once, you may exercise portions over multiple years. This can spread compensation income across tax years and may reduce the amount of income taxed at higher marginal rates.

Staged exercises do not guarantee lower tax. The stock price may rise, options may expire, and future tax law or employment circumstances may change. The strategy should be modeled using several stock-price assumptions.

3. Exercise earlier when the spread is smaller - If you expect substantial appreciation, exercising when the spread is smaller can reduce the amount treated as compensation income. Future appreciation would generally begin from the stock’s value at exercise and may receive capital-gain treatment when the shares are sold.

This strategy creates risk because the stock may decline, the options may become worthless, or the shares may remain illiquid. For private-company stock, the tax and valuation issues can be especially significant.

4. Sell other investments to diversify- If you exercise and hold employer shares, consider whether you should reduce other concentrated investments or sell some employer stock later. Diversification can be more important than pursuing the maximum possible stock appreciation.

The appropriate amount of employer stock depends on your income, age, financial obligations, risk tolerance, and other assets.

5. Plan for estimated taxes - The employer’s withholding on an NSO exercise may not cover the final tax liability. Review the additional federal, state, and local tax before exercising. A large exercise late in the year may require an estimated-tax payment or increased withholding from other wages.

6. Track Basis Carefully - Brokerage reporting may not always reflect the complete basis adjustment associated with option compensation. Keep:

  • The grant documents.

  • Exercise confirmation.

  • Fair market value at exercise.

  • W-2 reporting.

  • Shares sold.

  • Sale proceeds.

  • Commissions and fees, and

  • Form 1099-B information.

The compensation income reported on Form W-2 and the stock sale reported on Form 8949 and Schedule D must be coordinated so that the same income is not taxed twice.

7. Consider Charitable Giving of Appreciated Shares - If you exercise and hold shares that later appreciate, donating eligible appreciated stock to a qualified charity may provide a potential charitable deduction while avoiding recognition of some capital gain. This strategy involves substantiation rules, holding-period requirements, deduction limitations, and valuation issues.

It should be considered only after confirming that the shares are eligible and that the charitable deduction is useful in your circumstances.

PART TWO: INCENTIVE STOCK OPTIONS

An incentive stock option receives special tax treatment if it meets statutory requirements. Unlike an NSO, an ISO generally does not create regular taxable income when it is granted or exercised.

That does not mean the exercise is tax-free in every respect. Exercising and holding ISO shares can create an alternative minimum tax, or AMT, adjustment.

ISOs are subject to special rules, including eligibility requirements, exercise-price rules, transferrestrictions, and annual limitations. You should confirm that your employer’s documents identify the option as an ISO and that the shares qualify for ISO treatment.

Exercising an ISO - Suppose you exercise 1,000 ISOs with:

  • Exercise price: $20 per share;

  • Fair market value at exercise: $50 per share;

  • Total spread: $30,000.

For regular federal income-tax purposes, you generally do not recognize ordinary income merely because you exercised the ISO. However, the $30,000 spread is generally included in alternative minimum taxable income for AMT purposes.

The AMT adjustment is generally the difference between the stock’s fair market value at exercise and the exercise price. Your AMT basis in the shares is increased by the adjustment, even though your regular-tax basis is generally the exercise price.

This creates two basis records:

  • Regular-tax basis: Generally, the amount paid for the shares; and

  • AMT Basis:Generally, the exercise price plus the AMT adjustment.

The difference can create complicated calculations when the stock is later sold.

The ISO Holding-Period Requirements - To receive the most favorable tax treatment, you generally must sell the ISO shares:

  1. More than one year after the exercise date; and

  2. More than two years after the grant date.

A sale that satisfies both requirements is generally called a qualifying disposition. A sale before either period ends is generally a disqualifying disposition.

The holding periods apply separately to shares acquired through the option. If you exercise at different times, each group of shares may have a different holding-period schedule.

Qualifying Disposition - If you meet both holding-period requirements, the gain or loss is generally treated as capital gain or loss. For regular-tax purposes, the gain is generally measured using the exercise price as the basis.

For example:

  • Exercise price: $20 per share;

  • Sale price: $80 per share;

  • Gain: $60 per share.

If all holding-period requirements are met, the gain generally will qualify as long-term capital gain.

This treatment may be more favorable than ordinary wage income, but it requires you to accept the risk of holding the shares. The stock could decline after exercise, and the AMT may be due before you sell the stock.

Disqualifying Disposition - If you sell before satisfying either holding-period requirement, the transaction is a disqualifying disposition. In general, the amount of income treated as compensation is the lesser of:

  • The spread at exercise; or

  • The gain realized when the shares are sold.

Any additional gain above the compensation portion may generally be capital gain. If the shares are sold at a loss, special calculations may be required.

For example:

  • Exercise price: $20 per share;

  • Value at exercise: $50 per share;

  • Sale price: $55 per share.

The $30 spread at exercise is generally treated as ordinary compensation income in a disqualifying disposition. The additional $5 per-share increase may be capital gain, with the holding period determining whether it is short-term or long-term.

If the stock falls after exercise, the compensation amount may be limited by the sale price. For example, if the shares are sold for $35 after being exercised at $20, the compensation portion may be $15 per share rather than the original $30 spread.

A disqualifying disposition generally eliminates the intended long-term ISO tax treatment, but it may reduce or eliminate the AMT adjustment associated with continuing to hold the shares.

The AMT issue -The AMT is one of the most important risks associated with exercising and holding ISOs.

The potential AMT adjustment is based on the spread at exercise, not necessarily on cash received. Therefore, you could owe AMT even though you have not sold the stock and received cash from the appreciation.

Example:

  • 10,000 ISO shares.

  • Exercise price: $10.

  • Fair market value at exercise: $40.

  • Exercise cost: $100,000.

  • Stock value at exercise: $400,000.

  • AMT adjustment: $300,000.

The $300,000 adjustment does not automatically mean you will owe $300,000 of tax. The actual AMT depends on your filing status, other income, deductions, credits, prior AMT items, and the applicable exemption and phaseout rules. Nevertheless, a large adjustment can significantly increase your AMT exposure.

If the stock value later falls, you could face the particularly unpleasant situation of owing tax on value that no longer exists. The AMT calculation generally uses a higher basis for the shares, which can produce an AMT loss when the shares are sold. However, the timing and usability of any AMT credit can be uncertain.

Strategies for Managing ISO AMT Exposure

1. Exercise Smaller Amounts - Rather than exercising all ISOs at once, consider exercising a portion each year. This may reduce the spread included in AMT income and give you a better opportunity to evaluate the stock price and your tax position.

The number of shares that can be exercised without creating AMT varies by taxpayer. A calculation should include all income, deductions, other AMT preference items, and the expected stock value.

2. Exercise And Sell in the Same Year - Exercising and selling ISO shares in the same year creates a disqualifying disposition. This generally causes the spread to be treated as compensation income, similar to an NSO, but it may avoid the continuing ISO AMT adjustment.

This strategy sacrifices the possibility of qualifying-disposition treatment but limits the risk of paying AMT on shares that are still being held.

3. Exercise late in the year only after modeling the result - A late-year exercise can create a large AMT adjustment. Before exercising, estimate both regular tax and AMT using the expected exercise-date value.

Do not assume that a broker’s withholding or an employer’s payroll calculation covers AMT. ISO exercises may not produce ordinary wage withholding even though they may affect your tax return.

4. Sell enough shares to fund tax obligations - If you exercise and hold ISO shares, identify how the exercise price and possible AMT will be paid. Selling shares immediately may create a disqualifying disposition for those shares while allowing other shares to remain eligible for long-term treatment.

This requires careful lot identification and recordkeeping.

5. Consider possible AMT credit recovery - An AMT payment may generate a minimum-tax credit that can potentially be used in later years, subject to the applicable rules and available regular-tax liability. The credit may not be immediately usable, particularly if your income falls or your regular tax remains below the AMT calculation.

Do not treat a potential AMT credit as equivalent to cash in hand. Its value depends on your future tax returns.

6. Diversify gradually - Holding ISO stock until the qualifying-disposition date may produce favorable capital-gain treatment, but it can also leave you heavily concentrated in one company. A staged selling plan may balance tax objectives with investment risk.

The best strategy may not be the one producing the lowest theoretical tax. A lower tax bill is not beneficial if the stock loses substantially more value while you wait to sell.

Reporting and Recordkeeping - Employers generally provide information about ISO exercises on Form 3921. Keep this form with your exercise confirmation and brokerage statements.

When shares are sold, verify:

  • The grant date.

  • Exercise date.

  • Number of shares.

  • Exercise price.

  • Fair market value at exercise.

  • Sale date.

  • Sale proceeds.

  • Regular-tax basis.

  • AMT basis; and

  • Whether the sale was qualifying or disqualifying.

Brokerage firms may report proceeds and a basis that does not fully reflect the special ISO rules. The reported basis should be reviewed rather than accepted automatically.

FINAL PERSPECTIVE

Employee stock options can create wealth, but they also combine employment risk, investment risk, liquidity risk, and tax risk.

For NSOs, the central question is often whether to recognize wage income now and immediately sell, or exercise and hold while accepting the possibility of future capital appreciation and a stock-price decline.

For ISOs, the central question is often whether the potential benefit of a qualifying disposition justifies the cost and risk of holding the shares through the required periods, including possible AMT.

Before exercising, compare at least three scenarios:

  1. Exercise and sell immediately.

  2. Exercise and hold; and

  3. Exercise a portion and sell or hold the remainder.

The analysis should include taxes, withholding, transaction costs, expected cash needs, concentration risk, option expiration, and the possibility that the stock price may fall.

Before exercising nonqualified stock options or incentive stock options or allowing them to expire, contact this office for a personalized review. A review can help estimate the taxable income, withholding, potential alternative minimum tax, capital-gain consequences, and cash required under different exercise and sale strategies.

Planning in advance may help you avoid unnecessary taxes, prepare for possible tax payments, and choose an approach that better fits your overall financial goals.

PDF
Printable PDF

Have a Question About This Topic?

I confirm this is a service inquiry and not an advertising message or solicitation. By clicking “Submit”, I acknowledge and agree to the creation of an account and to the Terms of Use and Privacy Policy.

NEVER MISS A STORY.

Sign up for our newsletters and get our articles delivered right to your inbox.

Related Articles

Financial Flexing: When Looking Rich Keeps You From Getting Rich

Financial Flexing: When Looking Rich Keeps You From Getting Rich

September 17, 2026
Should You Give Your Kids Their Inheritance While You're Still Alive?

Should You Give Your Kids Their Inheritance While You're Still Alive?

September 9, 2026
When You Become the Family CFO

When You Become the Family CFO

September 4, 2026
Pay Off Debt or Invest? How Higher Interest Rates Change the Math

Pay Off Debt or Invest? How Higher Interest Rates Change the Math

September 1, 2026
ID: 20
Module: blog_search.mdl
PluginHeader:

Blog Search

ID: 9
Module: recent-posts-4.mdl
PluginHeader:

Recent Posts

Charitable Giving Strategies: Turning Generosity Into Effective Tax Planning

Charitable Giving Strategies: Turning Generosity Into Effective Tax Planning

October 27, 2026
Congress May Not Be Done With Taxes Yet: What to Watch in the Lame-Duck Session

Congress May Not Be Done With Taxes Yet: What to Watch in the Lame-Duck Session

October 26, 2026
November 2026 Business Due Dates

November 2026 Business Due Dates

October 23, 2026
ID: 21
Module: blog_categories.mdl
PluginHeader:

Blog Categories

  • Business Life Events
  • Business Success Stories
  • Calculators & Tools
  • Credit Issues
  • Education Planning
  • Elder Care & Planning
  • Employment
  • For Business
  • Friendly Reminders
  • Health Care Issues
  • Health Care Reform
  • HR & People Management
  • Life Events
  • Looking to Invest
  • Newsworthy
  • Personal Finance
  • Record Keeping Tips
  • Retirement Planning
  • Tax Central
  • Tax Organizers
  • Tax Problems
  • Tips for Verticals & Niches
  • Videos & Info Graphics
 

Read Our Reviews

 
Recent review:
2/8/2019
Very professional, informative and fast, I was absolutely happy.
Overall rating:
(14 reviews)
read all reviews...
 

Please Take a Moment to Rate Us

Read Unbiased Consumer Reviews Online at AngiesList.com
angieslist.com/review/7739563


10,000 Small Businesses Alumni Member

Chamber South Affiliated Business

Doral Chamber of Commerce


TaxBuzz Verified
  • Home
  • About
    • About Us
    • Meet the Team
    • Referrals
    • Privacy Policy
    • Careers
    • FAQ
  • Services
    • Tax Preparation and Planning
    • Accounting & Bookkeeping
    • Business Consulting
    • Payroll
    • IRS Tax Problems
    • Audit, Review & Compilation
    • Quickbooks Services
    • Part Time CFO Services
    • Business Valuation
    • Cost Segregation
  • Learning Center
  • Community Involvement
    • Goldman Sachs Small Business 10,000
    • Client Appreciation 05/28/2015
    • Leadership Miami
  • Testimonials
  • 中文
    • 關於我們
    • 服務項目
    • 2018 年 新 税 法
  • Contact
 
Ivy Accounting, Tax & Advisory
8950 SW 74th Court, Suite 1612
Miami, FL 33156 USA
(786) 227-6928
info@ivy-cpa.com
Stay Connected
 
A ? R G ; B = D
©2026 Ivy Accounting , Tax & Advisors   Terms of Use   Privacy Policy Accessibility Statement  
Powered by CountingWorks PRO